Bitget UEX Daily Report | Software Sector Rebounds; Meta Signs Massive Chip Deal with AMD; HP Drops Over 6% After Hours; Circle to Release Earnings
Author: Bitget
I. Key News Highlights
Federal Reserve Updates
Fed Officials Signal AI May Lift Neutral Interest Rate
- Multiple Fed governors and presidents commented on labor market conditions and the inflation trajectory: Cook noted that AI is triggering an intergenerational shift, potentially pushing up the neutral interest rate in the near term and increasing inflation risks; Collins expects inflation to ease later this year; Goolsbee emphasized the need for more evidence confirming sustained disinflation before proceeding with further rate cuts. Market impact: Rate-cut expectations are now further anchored to June–July; the U.S. dollar gains support; U.S. Treasury yields face short-term pressure; volatility in risk assets may remain elevated.
Global Commodities
Global Tanker Freight Rates Surge to Near Six-Year High
- VLCC daily charter rates on the Middle East–China route have exceeded $170,000—tripling since the start of the year; U.S.–Iran negotiations, geopolitical supply shifts, and a surge in vessel orders by South Korean shipowners collectively pushed freight rates to their highest level since April 2020. Market impact: Rising oil transportation costs will be passed through to end-user oil prices, offering short-term support to WTI and Brent crude; however, if negotiations progress smoothly, the geopolitical risk premium may recede.
Macroeconomic Policy
Trump’s State of the Union Address Announces Tech Giants to Bear Energy Costs of AI Data Centers
- The government reached an agreement with several unnamed tech companies requiring enterprises to cover electricity and infrastructure expenses for their data centers—aimed at preventing consumer electricity price surges; ADP data shows private-sector job additions averaged 12,750 over the past four weeks—continuing a four-week improvement trend but still below last year’s peak. Market impact: While easing fiscal and household burdens, the policy increases capital expenditure pressure on tech firms; the sustainability of the AI investment boom has become a new focal point for markets.
II. Market Recap
Commodities & FX Performance
- Spot Gold: Up 0.18% to $5,153/oz, remaining within its upward trend channel
- Spot Silver: Up 0.2% to $87.42/oz
- WTI Crude Oil: Up 0.72% to $66.11/bbl, with geopolitical negotiations and rising freight costs offsetting each other
- U.S. Dollar Index: Down 0.07% to 97.83, supported by cautious Fed commentary
Cryptocurrency Performance
- BTC: Down ~1.05% to ~$64,189—facing short-term support tests after four consecutive down days
- ETH: Down ~0.7% to ~$1,850—beta-driven losses amplified
- Total Crypto Market Cap: Up ~0.2% to $2.29 trillion—driven primarily by declining risk appetite
- Liquidations: Total liquidations ~$340 million, dominated by long positions (~$249 million), concentrated among long positions
U.S. Equity Index Performance
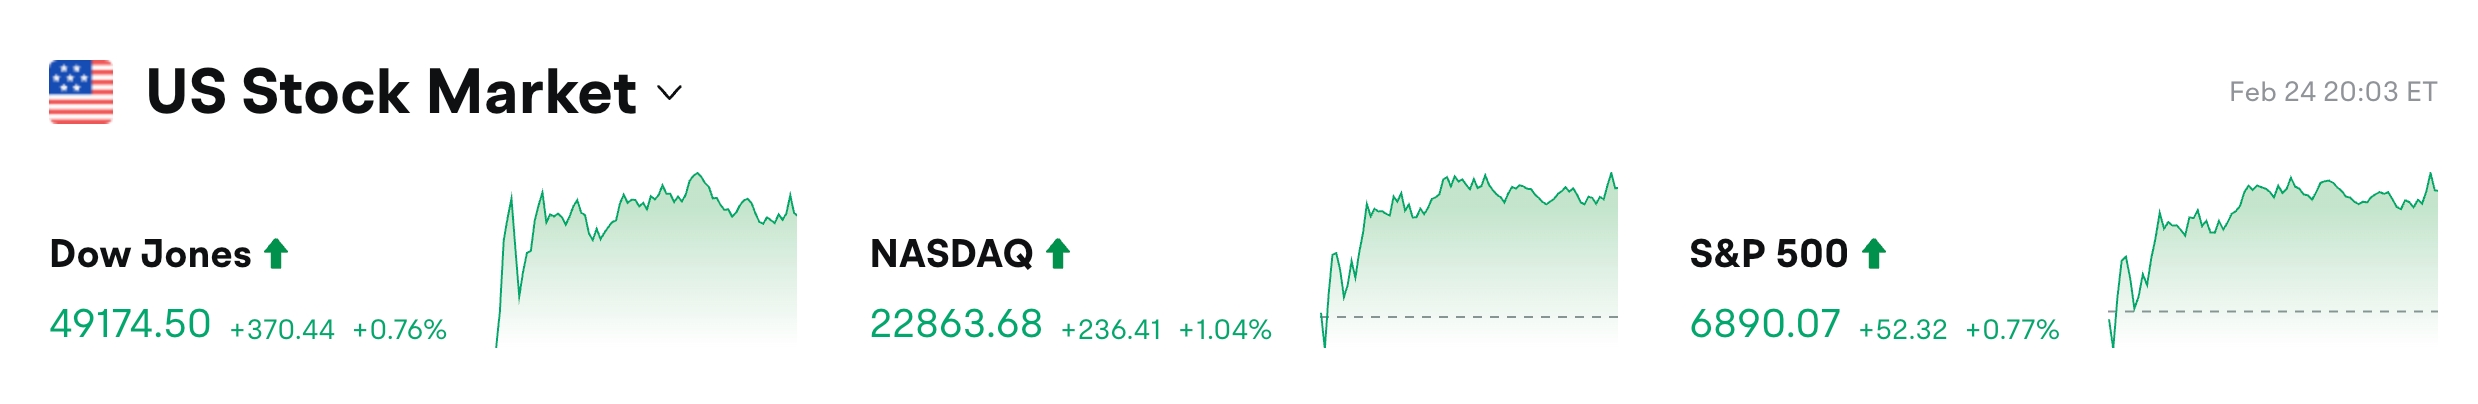
- Dow Jones Industrial Average: Up 0.76% to 49,174.5 points—rebounding consecutively to recover prior-day losses
- S&P 500: Up 0.77% to 6,890.07 points—software and technology stocks led gains
- Nasdaq Composite: Up 1.04% to 22,863.68 points—significantly driven by AI application software stocks
Tech Giants’ Developments
- AAPL: +2% or more—boosted by rumors of a touch-screen MacBook Pro launch this fall
- AMZN: +1% or more—supported by overall positive tech sentiment
- GOOGL: Down 0.19%—signed a 20-year “power agreement” with AES to support global cloud services and AI expansion; remains a medium- to long-term positive
- META: Significant rally—directly catalyzed by AMD’s massive chip deal
- MSFT: +1% or more—aligned with broader software sector recovery
- NVDA: Slight gain of 0.68%—pre-earnings caution dominates sentiment
- TSLA: +2% or more—benefited from sector rotation. Core drivers: Anthropic’s conference signaled “collaboration—not replacement,” easing software-stock concerns; Meta–AMD’s landmark agreement boosted AI infrastructure themes.
Sector-Specific Moves
Software / AI Application Sector led gains
- Representative stocks: Figma +11%, Roblox +7%, Salesforce +4%
- Catalysts: Anthropic launched enterprise agents and partnered with traditional software vendors; institutions including Wedbush argue AI’s disruption risk to existing workflows has been overstated
Memory / Storage Sector declined notably
- Representative stocks: SanDisk (SNDK) –4.2%, Micron slightly down, HPQ down >5.75% after hours
- Catalysts: Citron Research launched a surprise short report arguing NAND’s cyclical nature has been misinterpreted as an AI moat; expectations of Samsung’s capacity recovery intensify supply-side pressure; HPQ’s earnings revealed rising memory costs weighed on guidance
III. In-Depth Stock Analysis
1. Meta Platforms — Landmark “Chip + Equity” Agreement with AMD
Event Summary: Meta announced a multi-year agreement with AMD to deploy up to 6 gigawatts of AMD Instinct GPU compute power, valued at approximately $60 billion; simultaneously, Meta secured the right to purchase up to 160 million shares of AMD common stock at $0.01 per share (representing ~10% of AMD’s equity)—a milestone-triggered exercise. Initial shipments are scheduled for H2 2026, featuring custom MI450-architecture GPUs and Venice CPUs.
Market Interpretation: Analysts view this move as helping AMD accelerate its catch-up to Nvidia in the AI chip market; the equity linkage further strengthens strategic alignment between both parties, alleviating market concerns over AMD’s long-term competitiveness.
Investment Implications: The diversification trend in AI capex is clear; valuation recovery potential opens for second-tier chipmakers like AMD. Investors are advised to monitor upstream and downstream beneficiaries across the supply chain.
2. AMD — $60 Billion Chip Order and Equity Tie-Up with Meta
Event Summary: Same agreement details as above; AMD’s stock surged intra-day by over 8.77%, closing near its session high.
Market Interpretation: Wall Street views this as AMD’s “second Nvidia-scale” order; coupled with performance-based warrants, long-term revenue and stock price linkages gain greater certainty.
Investment Implications: Strong short-term catalyst; medium- to long-term outlook depends on actual shipment progress—suitable for AI hardware-themed allocations.
3. HP Inc — Q1 Revenue Beats Expectations, but Memory Costs Weigh on Guidance
Event Summary: FY2026 Q1 revenue totaled $14.44 billion, up 6.9% YoY and exceeding consensus; Q2 non-GAAP EPS guidance of $0.70–$0.76 (midpoint $0.73) fell below consensus of $0.75; full-year guidance was maintained but skewed toward the lower end. CFO explicitly cited persistent memory price increases as the primary headwind. Shares fell >6% after hours.
Market Interpretation: Analysts lowered near-term earnings forecasts, emphasizing cyclical cost pressures outweighing demand recovery.
Investment Implications: PC/printing business fundamentals remain solid; watch for inflection in memory pricing—suitable for tactical trading.
4. Alibaba — Launch of Qwen 3.5 Mid-Sized Model Series
Event Summary: The Qwen team launched the Qwen3.5 mid-sized model series (Flash, 35B-A3B, 122B-A10B, 27B, etc.), employing a hybrid architecture that significantly reduces activated parameters, outperforms previous versions on agent tasks, and supports contexts up to one million tokens.
Market Interpretation: Open-source + efficiency-focused strategy bolsters domestic AI competitiveness with pronounced cost advantages.
Investment Implications: China’s AI application deployment is accelerating; investors should monitor long-term opportunities in Alibaba Cloud and related ecosystem players.
5. Circle — Stablecoin Leader to Release Q4 Earnings
Event Summary: Circle (CRCL) will release its Q4 and full-year FY2025 results before market open on February 25; USDC circulation has surpassed $74 billion, doubling YoY.
Market Interpretation: Markets are focused on how interest-rate environments impact reserve income and whether payment-business growth can offset such headwinds.
Investment Implications: Stablecoin ecosystem expansion remains intact; monitor USDC market share and progress toward diversified revenue streams.
IV. Cryptocurrency Project Updates
- Circle’s Q4 earnings announcement approaches; USDC circulation continues doubling.
- Analysis: Bitcoin’s “fair-value gap” points to $45,000; AI-related concerns weigh on equities and gold.
- Bitwise acquires staking provider Chorus One, strengthening multi-chain staking footprint.
- Ethereum ecosystem DeFi TVL sees modest recovery but remains under pressure.
- 21Shares’ spot SUI ETF begins trading on Nasdaq.
V. Today’s Market Calendar
Data Release Schedule
| 21:30 | USA | Durable Goods Orders | ⭐⭐⭐⭐ |
| 22:00 | USA | New Home Sales | ⭐⭐⭐ |
Key Event Previews
- Circle Earnings: Pre-market release—USDC circulation and payment business progress
- NVIDIA Earnings: Post-market release—critical test of AI demand validation
- Trump’s State of the Union Address: Evening, Eastern Time—details on AI energy policy
Bitget Research Institute View:
U.S. software stocks rebounded sharply following Anthropic’s conference, with all three major indices rising—a reflection of rapid market acceptance of the AI narrative of “collaboration, not disruption.” The landmark $60 billion Meta–AMD agreement further bolstered confidence in the chip supply chain. However, a wave of Fed officials signaling a potential rise in the neutral interest rate has rendered the path to rate cuts more cautious. Precious metals and crude oil are supported by geopolitical and freight-cost factors, while the U.S. dollar edged higher. Overall, institutions view the current rally as technical recovery rather than a trend reversal. Investors are advised to monitor NVIDIA’s earnings and the implementation of Trump’s energy policy for directional cues on risk appetite. Short-term volatility is likely to remain elevated; portfolio allocation should balance AI hardware exposure with defensive assets.