


Bitget UEX Daily | US Treasury Options Shift to Betting on 2027 Rate Cuts; September Rate Hike Expectations Cool Significantly; AI Industry Chain Under Collective Pressure

I. Hot News
Federal Reserve Updates
US Treasury Options Shift to Bet on 2027 Rate Cut; September Rate Hike Expectations Cool Significantly
- US July inflation, retail sales, and consumer confidence weakened, coupled with an unexpected decrease of 23,000 in non-farm payrolls, leading to trades hedging against a Federal Reserve policy reversal in the interest rate options market.
- Investors bought September expiration options betting on maintaining interest rates unchanged, while simultaneously positioning for March and June 2027 SOFR call options.
- Probability of a September rate hike dropped from a high of about 68% two weeks ago to about half; interest rate swaps imply only about 9 basis points hike for the September meeting. Market Impact: Repricing of the policy path alleviates some tightening concerns, but long-term yields remain high, divergence between short-end and long-end expectations creates divergent pressure on growth stocks.
International Commodities
Trump Pauses Contact with Iran, Geopolitical Stalemate Continues
- US officials stated Trump has requested the negotiation team (including Vice President Vance, Envoy Witkoff, and Kushner) to pause contact with Iran.
- White House strategy shifted from "hit hard ASAP" to long-term "chokehold", instructions given after active discussions previously. Market Impact: Pause in Hormuz-related negotiations exacerbates supply uncertainty, oil prices gain geopolitical support, inflation stickiness concerns continue.
Macro Policy
Multiple US States Tighten Data Center Power Regulation, AI Infrastructure Becomes Midterm Election Issue
- Pennsylvania requires data centers to自备 power and increase clean energy proportion; Texas launched grid access audit; New York paused new large data center construction.
- Bank of America strategists listed it as a midterm election variable, tighter regulation may affect AI capital expenditure pace. Market Impact: Power and community constraints increase AI infrastructure landing costs and uncertainty, related equipment and power suppliers gain attention, tech hardware valuation under pressure.
II. Market Review
Commodities & Forex Performance
- Spot Gold: About $4,343/oz, +0.2%
- Spot Silver: About $63/oz, -0.52%
- WTI Crude: About $85/barrel, +0.87%
- Brent Crude: About $89/barrel, +0.56
- US Dollar Index (DXY): About 99.645, slight fluctuation
Driver Analysis: Trump pausing contact with Iran continues Hormuz uncertainty, oil prices gain geopolitical support. Gold oscillates between warming rate cut expectations and high long-term bond yields, silver performance diverges under dual influence of industry and safe haven. US Treasury options show September rate hike probability cools significantly, but 30-year yields remain high, limiting precious metals upside space. Institutional views believe short-term commodities are jointly dominated by geopolitics and interest rate path repricing, high oil prices may reinforce inflation stickiness narrative, asset linkage reflects as geopolitical stalemate→oil price support→inflation expectations→policy path reassessment.
Cryptocurrency Performance
- BTC: About $64,600, +0.31%
- ETH: $1915, +0.32%
- Total Cryptocurrency Market Cap: $2.29 trillion, +0.2%
- Market Liquidations: 24-hour liquidations $205 million, long liquidations $119 million.
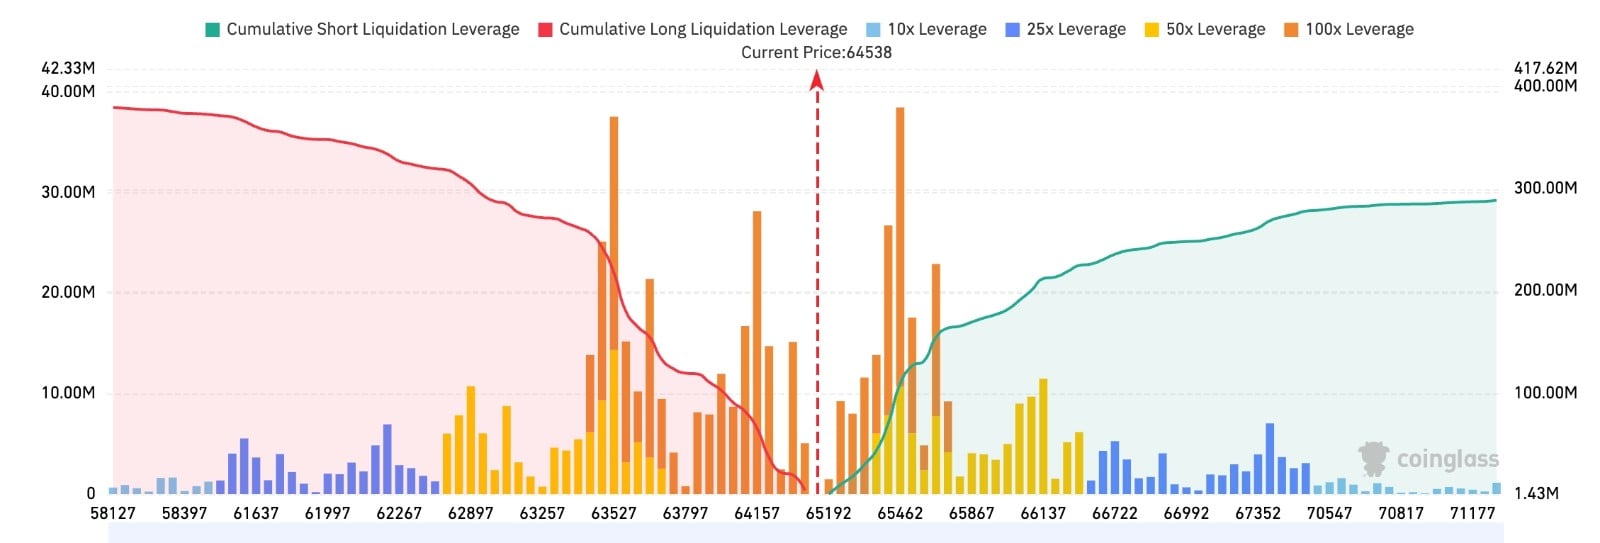
- Bitget BTC/USDT Liquidation Map: Current BTC price about $64,538, large amount of high leverage (50x/100x) short liquidation orders聚集 above 65,000–66,000 range, breakthrough easily triggers short cascade liquidation and amplifies upward momentum; long liquidation pressure in 63,000–64,000 area below has partially released, short-term leverage center of gravity obviously biased upwards.
- Spot ETF Net Inflow/Outflow: Yesterday net inflow $298 million, current dynamic net inflow $46 million.
Driver Analysis: US stock AI sector pullback and high long-term bond yields suppress risk appetite, crypto market follows oscillation. Whales net increased holdings by about 43,000 BTC in past 60 days, showing medium to long-term funds still laying out at lows. ETF fund flow volatility coexists with leverage liquidations, institutional consensus points to range oscillation, focus on transmission of interest rate path repricing and geopolitical developments to risk assets.
US Stock Index Performance
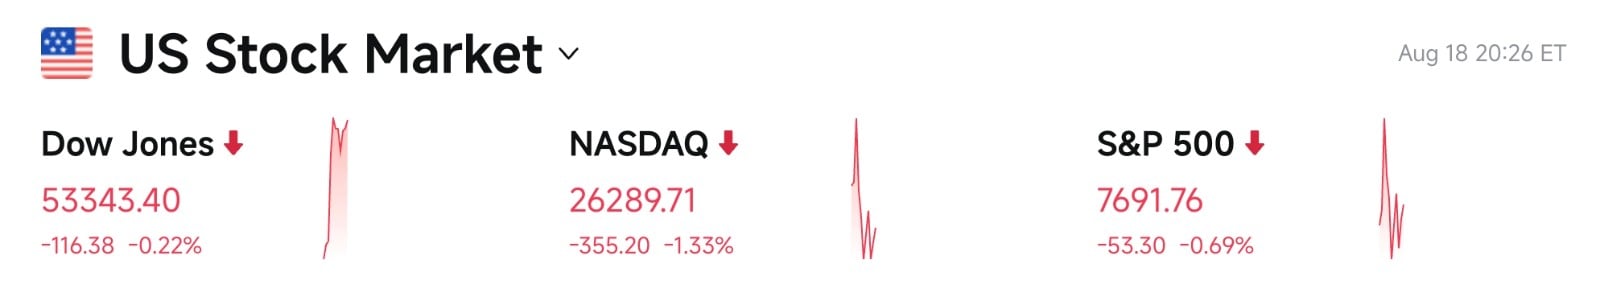
- Dow: Closed 53,343.40 points, down 0.22%
- S&P 500: Closed 7,691.76 points, down 0.69%
- Nasdaq: Closed 26,289.71 points, down 1.33%, tech and semiconductor drag obvious
Tech Giants Dynamics
- NVDA: About $219.74, down 2.34%
- AAPL: About $310.03, up 1.45%
- MSFT: About $481.63, up 0.27%
- GOOGL: About $344.20, up 0.06%
- AMZN: About $259.45, down 0.71%
- META: About $543.67, down 4.45%
- TSLA: About $336.87, down 0.72%
Performance Summary and Driver Analysis: Seven Giants obviously diverged. Apple, Microsoft, Google relatively resistant or closed higher, Nvidia, Meta led declines. AI hardware and semiconductor sectors significantly pulled back under dual pressure of valuation and regulation, funds partially rotated to software and defensive sectors. US Treasury options show rate cut expectations moved forward, but high long-end yields and tighter data center regulation jointly suppress high capital expenditure growth stocks, individual stock driver differences highlighted.
Sector Movement Observation
Semiconductor/Memory Significant Pullback
- Representative Stocks: SK Hynix down about 9.2%, SanDisk down about 9.01%, Broadcom down about 3.17%.
- Drivers: AI heat cools, valuation digestion and South Korea market drag, funds withdraw from hardware links.
Optical Communication Concepts Significant Decline
- Representative Stocks: Coherent down about 12.75%, Lumentum down about 9.87%.
- Drivers: AI optical module demand expectations cool phaseally, sector high elasticity amplifies decline.
Pharmaceutical and Dividend Sectors Relatively Strong
- Representative Stocks: Johnson & Johnson created new closing high, Eli Lilly etc. close to historical highs.
- Drivers: Funds rotate from high valuation AI themes to defensive and steady growth sectors.
III. In-depth US Stock Interpretation
1. Coherent (COHR) - Optical Communication Leader Significant Pullback
Event Overview: Coherent stock price fell about 12.75% in a single day, becoming one of the targets with the largest decline in the AI optical communication sector that day. Company previously announced fiscal year Q4 performance exceeded expectations (revenue about $2.05 billion, YoY growth about 34%, non-GAAP EPS $1.74), and gave higher than expected next quarter guidance, stock price surged over 7% in the previous trading day. But obvious profit-taking occurred on August 18, simultaneously Tradr 2X Short COHR Daily ETF (COHQ) listed that day, providing leverage tools for short funds, further amplifying decline. Market Interpretation: Institutions believe this pullback mainly reflects technical correction of high elasticity targets after performance realization, coupled with AI hardware sector overall risk appetite decline and Anthropic revenue expectations not meeting some market rumors. Fundamentals still recognized, but short-term valuation digestion and leverage product introduction amplify volatility. Investment Implications: Optical communication demand logic unchanged, but high volatility requires stricter position and timing management, focus on follow-up orders and capacity landing situation.
2. Lumentum (LITE) - Optical Module Sector Under Pressure Together
Event Overview: Lumentum stock price fell about 9.87%, weakening together with Coherent, Credo and other optical communication targets. Market attributes pressure to AI optical interconnect high valuation digestion, profit-taking after previous day's large gain, and broader semiconductor and AI hardware sell-off. Market Interpretation: Analysts point out optical communication sector previous gains were large, static valuation high, once macro or sentiment turns quick pullback occurs. William O'Neil and other institutions still maintain buy rating, but short-term fund flows to defensive and software sectors. Investment Implications: As AI data center optical module core target, medium-term logic remains, but need to guard against valuation volatility and sector rotation risk.
3. Credo Technology (CRDO) - High-Speed Connection Chips Lead Decline
Event Overview: Credo Technology stock price fell about 13%, among the top decliners in AI optical and high-speed connection related targets. Company benefits from data center high-speed SerDes and optical interconnect demand, but followed entire AI hardware and optical sector significant pullback on August 18. Market Interpretation: Institutions view this decline more as result of sectoral risk appetite decline and previous gain digestion, rather than company fundamentals sudden deterioration. High beta attribute amplifies elasticity when sentiment turns. Investment Implications: Suitable as AI infrastructure high elasticity allocation, but need to closely track data center capital expenditure pace and competitive landscape changes.
4. SanDisk (SNDK) - Storage Sector Significant Pullback
Event Overview: SanDisk stock price fell about 9%, under pressure together with Micron, Seagate and other storage related individual stocks. Market worries about high interest rate environment suppression on growth stock valuation, and AI storage demand expectations phaseal cooling. Market Interpretation: Analysts believe storage cycle and AI demand still have medium to long-term support, but short-term obviously affected by high long-term bond yields and funds rotating from hardware to other sectors. Previous trading day some storage stocks surged due to policy and demand narrative, followed by profit-taking. Investment Implications: Storage supply-demand gap logic remains, but short-term volatility increases, suggest focusing on follow-up financial reports and capital expenditure guidance.
5. Apple (AAPL) - Counter-Trend Close Higher Amid Tech Pullback
Event Overview: Apple stock price rose about 1.45%, performed relatively strong amidst Nasdaq sharp decline and AI hardware collective pullback, becoming one of the few targets closing higher among the Seven Giants. Market Interpretation: Institutions view Apple as relatively defensive tech allocation, hardware cycle and service business provide certain buffer, funds partially flow to more certain consumer electronics leader when high valuation AI hardware sold off. Investment Implications: Suitable as steady exposure in tech sector, focus on new product cycle and AI function landing contribution to long-term growth.
IV. Market & Project Dynamics
1. US Treasury options market significantly shifted to bet on 2027 rate cut, September rate hike probability fell from high position to about half.
2. VanEck research team pointed out, 8 out of 12 market surrender indicators they track have lit up, indicating Bitcoin's nearly 11-month pullback may be nearing end. Bitcoin oscillated in $58,000 to $66,500 range since June, currently about $64,700, still about 48% lower than October 2025 historical high. US spot Bitcoin ETF recorded nearly $300 million net inflow on Monday, strongest single-day performance since May 5. VanEck pointed out, previous three Bitcoin bear market cycles from peak to maximum drawdown averaged 12.7 months, currently entered 11th month, calculated by historical cycle rules, market may enter accumulation phase in September to November. But team reminded, historically after surrender indicators集中 trigger, short-term returns not necessarily ideal—90-day and 180-day average returns under similar situations instead lower than market benchmark. Simultaneously, long-term holders reduced holdings by about 356,000 BTC in past 30 days, holdings dropped to 11.84 million, proportion of total circulating supply fell below 60% for first time in several months.
3. US Securities and Exchange Commission (SEC) proposed new rule "Regulation Crypto Assets" (Crypto Asset Regulation Rules), aiming to provide compliant path for investments involving digital assets, allowing some issuance exemptions to comply with Securities Act. New rule described as "tailored issuance system", aiming to help raise funds while protecting investors, different from innovation exemption. This new rule includes "Startup Exemption", allowing issuances up to $5 million exempt from Securities Act of 1933 registration requirements within four years; and "Financing Exemption", allowing issuances up to $75 million exempt for one year. Proposal also includes a safe harbor provision, allowing digital assets no longer deemed securities after meeting specific conditions and "ceasing all management activities". Proposal comment period is 60 days.
4. Bitcoin whales net increased holdings by about 43,000 in past 60 days, medium and super-large holders simultaneously accelerated buying.
5. Anthropic plans to expand credit line and advance possible autumn IPO, revenue has exceeded OpenAI. OpenAI Q2 revenue $6.7 billion, higher than Q1's $5.7 billion, QoQ growth 18%. Simultaneously, company operating profit margin further declined, losses expanded. Some investors disappointed with this performance, reason being OpenAI revenue growth lagged behind competitor Anthropic.
6. Bank of America analyst Vivek Arya calculated via free cash flow sum-of-the-parts valuation model believes, Nvidia current stock price has about 34% to 50% discount compared to its value, even including related risks of providing financing for ecosystem. He pointed out, market may have overestimated Nvidia's risks on AI investment, thereby bringing "attractive buy opportunity". Report shows, Nvidia has committed to invest about $300 billion funds into projects like OpenAI Ohio data center campus and ecosystem partners, of which about $70 billion is equity investment, about $230 billion is residual value guarantee or buyback commitment. BofA maintains "Buy" rating and $350 target price for Nvidia.
V. Today's Market Calendar
Data Release Schedule
| Focus | US | Relevant Economic Data and Fed Officials' Speeches | ⭐⭐⭐ |
Important Event Preview
- US-Iran Contact Dynamics: Continuously track follow-up progress after Trump pauses negotiations.
- Data Center Regulation: Focus on impact of each state's policy landing on AI capital expenditure.
- AI Company Dynamics: Anthropic financing and potential IPO progress.
August 19 (Wednesday)
- ★★★★★ Federal Reserve releases July FOMC Minutes (UTC+8 timezone evening), succeeding last week's CPI as this week's most important macro event. Focus on observing July meeting 3 votes against maintaining interest rates hawkish divergence details, depth of discussion on inflation stickiness, labor market and September policy path;
- Target (TGT), Lowe's (LOW), TJX, Analog Devices (ADI) release earnings before market, test retail consumption health and semiconductor/AI related demand (ADI focus on industrial, data center power and communication ends);
- EIA Crude Oil Inventory Data.
August 20 (Thursday)
- US releases August Philadelphia Fed Manufacturing Index, Weekly Initial Jobless Claims, July Leading Indicators;
- ★★★★ Walmart (WMT) releases earnings before market, core test low-end consumption resilience, grocery and general merchandise demand; Alibaba (BABA), NetEase (NTES), Deere (DE) etc. simultaneously;
- Ross Stores etc. after market.
August 21 (Friday)
- ★★★★ US releases August S&P Global Manufacturing/Services PMI Preliminary, verify economic expansion momentum and soft landing continuity;
- Other major events fewer.
*Last week CPI/PPI slowed after rate hike expectations obviously cooled, if minutes show limited divergence and retail/housing data robust, soft landing trade and growth stocks有望 continue; conversely if minutes hawkish or consumption guidance weak, may re-raise tightening pricing and test high valuation sectors. Expected market volatility medium to high, focus on minutes wording and retail earnings beat or miss pricing reaction.
Institutional Views:
Investment bank analysts believe, US Treasury options show September rate hike expectations obviously cooled, policy path repricing provides certain buffer for risk assets, but high long-term yields and AI hardware valuation digestion still suppress growth stocks. Trump pausing contact with Iran continues geopolitical uncertainty, oil prices gain support. Data center regulation tightening increases AI infrastructure landing constraints, funds rotate from semiconductor and optical communication to pharmaceutical, software etc. sectors. Crypto market maintains oscillation amidst whale increased holdings and ETF volatility. Overall strategy suggests focusing on interest rate path reassessment and regulation landing progress, remain prudent on high valuation AI hardware, simultaneously observe defensive sector sustainability.
Disclaimer: Above content compiled by AI search, human verification only for publication, not intended as any investment advice. Data in the text inevitably contains deviations, please refer to real-time market data.















