Crypto Financing Halves in Q1: Why Are Stablecoin Payments Attracting Capital Against the Trend?
Author: Wu Blockchain
Compiled by: TechFlow
TechFlow Editor's Note: Crypto VC funding halved quarter-over-quarter in Q1, yet stablecoin payments became one of the few sectors continuing to secure large funding rounds consecutively. For practitioners, this marks capital shifting from "token narratives" to "real revenue," and also means stablecoins are transitioning from trading tools to payment infrastructure. However, on-chain trading volume does not equal real payment volume; compliance, fiat on/off ramps, and banking relationships remain key bottlenecks.

Overall funding has cooled: In Q1 2026, crypto VC funding decreased approx 50% QoQ, capital increasingly concentrated on mature companies with existing customers, revenue, and significant transaction volume.
Stablecoin payments grow against the trend: Companies like Rain, OpenFX, RedotPay, Mesh, Conduit continue to secure large funding in card issuance, cross-border payments, FX liquidity, wallets, banking connections, and settlement.
VCs focus on infrastructure: Stablecoins support 24/7 cross-border settlement, infrastructure providers can generate revenue via transaction fees, FX spreads, card services, and APIs.
Momentum should not be exaggerated: On-chain stablecoin volume does not equal real-world payment volume, funding remains concentrated in a few top companies. Compliance, fiat on/off ramps, local banking relationships, and service commoditization remain key challenges.
Where capital may flow next: Cross-border B2B payments, stablecoin co-branded cards, bank-stablecoin connections, multi-chain payment orchestration, and AI agent payments may continue to attract investment.
Crypto VC funding slowed sharply in Q1 2026. According to Galaxy Research, crypto VCs invested about $4 billion across 355 deals. This means funding amount decreased 50% QoQ, deal count decreased 16%. Meanwhile, number of newly established crypto VC funds dropped to lowest level since Q3 2020.
However, slowdown did not affect all companies equally. Galaxy Research pointed out main reason for overall funding decline is reduction in super-large late-stage rounds, seed and early stage activity continues. Meanwhile, 57% of capital flowed to late-stage companies, indicating investors became more picky. They no longer support companies heavily relying on tokens and market sentiment. Instead, they are increasingly willing to fund enterprises with existing customers, revenue, and significant payment volume.
Strictly speaking, stablecoin payments is not the largest category of crypto VC investment. In Q1 2026, companies in trading, exchanges, investment, and lending sectors raised about $2.6 billion total, continuing to lead other sectors significantly.
More accurately, stablecoin payments has become one of the few sectors still capable of consistently generating large funding rounds. In an environment where overall funding is difficult, it continues to complete financing consecutively.
Stablecoins Are Shifting from Trading Tools to Payment Infrastructure
VC interest in stablecoin payments started with the continuous expansion of stablecoins themselves.
A study released by the Federal Reserve in April 2026 showed that as of April 6, total stablecoin market cap reached about $317 billion. This is growth of over 50% compared to early 2025.
Adjusted data from Visa and Artemis shows stablecoins processed about $10.2 trillion in volume over the past 12 months, up 63% YoY. However, about 36% of adjusted stablecoin volume in 2025 came from deposits and withdrawals at centralized exchanges. This means this aggregate figure cannot be equated to payments for goods and services.
Historically, stablecoins were mainly used to transfer funds between exchanges, or as temporary safe-haven assets during crypto market volatility. Nowadays, companies are attempting to connect this on-chain liquidity with the traditional financial system. They achieve this through cross-border B2B payments, remittances, payroll distribution, corporate treasury management, card payments, bank accounts, and FX settlement.
This shift also changed the structure of stablecoin investment. Investors no longer only support stablecoin issuers. They are looking for opportunities across the entire payment stack, including dedicated blockchains, stablecoin issuance and orchestration, wallets, fiat on/off ramps, FX liquidity, card issuance, banking connections, clearing, and redemption.
Each layer has formed an independent startup category.
Recent Stablecoin Payment Funding
The following is not complete industry data, but highlights representative funding rounds announced since 2025. These companies are located at different layers of the stablecoin payment stack and should not be viewed as having the same business model.
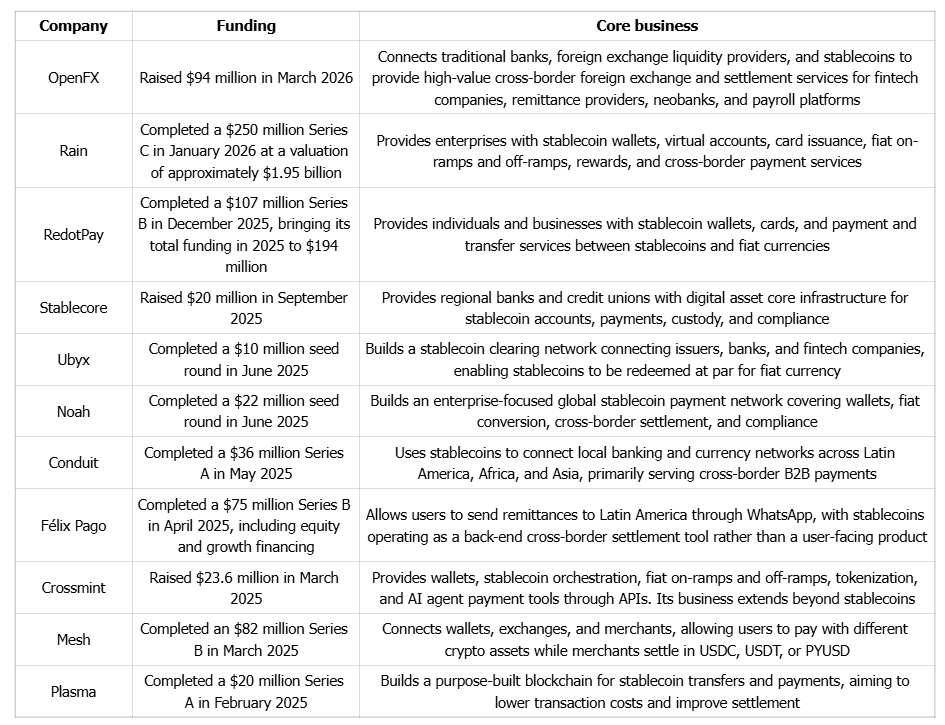
These companies indicate that stablecoin payments cover several distinct business models.
Rain, RedotPay, and Félix Pago are closer to the application and distribution layer, solving how users remit, hold, and spend stablecoins. OpenFX, Conduit, and Noah focus on cross-border payments, FX liquidity, and international settlement. Mesh and Crossmint provide wallet and payment orchestration tools. Stablecore and Ubyx connect banks, issuers, and stablecoin clearing systems, while projects like Plasma attempt to redesign the underlying blockchain infrastructure supporting stablecoin payments.
Therefore, this wave of investment is not just betting on one specific stablecoin. It is more broadly betting on a type of infrastructure—these infrastructures will be indispensable if stablecoins are widely used as payment and settlement tools.
Capital Is Favoring Companies with Real Business Metrics
Unlike early crypto companies that mainly relied on future narratives, stablecoin payment companies that recently secured funding are increasingly disclosing transaction volume, customer count, and revenue.
Rain completed a $250 million Series C funding in January 2026, about four months after its Series B, and about ten months after Series A. The company stated its active card users grew 30x in one year, annualized payment volume grew 38x. Rain currently processes about $3 billion in annualized transaction volume for over 200 partners.
OpenFX completed a $23 million seed funding round in 2025, and raised another $94 million about ten months later. The company told Reuters its annualized payment volume increased from $4 billion a year ago to over $45 billion. The company also stated over 98% of transactions are completed within 60 minutes, whereas traditional FX settlement usually takes two to five business days.
RedotPay stated that as of November 2025, it has over 6 million registered users in over 100 markets. The company reported annualized payment volume over $10 billion, annualized revenue over $150 million, and has achieved profitability.
Most of this data is self-reported and may not be independently audited. Definitions of payment volume, transaction volume, and annualized revenue may also differ among companies, thus making direct comparison difficult.
Nevertheless, these disclosures reflect a broader shift. Stablecoin payment companies are attempting to prove their value using traditional fintech metrics, rather than relying solely on wallet addresses, token prices, and community size.
Why Are Stablecoin Payments Attracting VC Attention?
1. Cross-Border Payments Have Long Had Efficiency Issues
Traditional cross-border payments usually involve originating bank, correspondent bank, clearing network, receiving bank, and local payment institutions. Each participant operates according to their own business hours, ledgers, and compliance processes. Therefore settlement may take several days.
Payment companies hoping to provide instant transfers across multiple countries may also need to pre-deposit bank account funds in each market. Although funds are not yet used, they must remain in different jurisdictions to ensure customers can withdraw in time. This brings heavy working capital burdens.
Stablecoins cannot automatically solve every link in this process. But they can provide a unified settlement asset that operates 24/7. Payment companies can transfer stablecoins on-chain, then rely on local partners to convert them into local currency.
This applies to cross-border B2B payments, remittances, global payroll, and internal corporate fund transfers. Faster settlement and lower pre-deposit fund requirements can directly create business value.
2. Revenue Models for Payment Infrastructure Are Relatively Clear
Stablecoin payment companies usually do not rely on token appreciation for revenue. Instead, they can charge transaction fees, FX spreads, card issuance fees, account management fees, API subscription fees, and fiat on/off ramp fees.
These revenue models are not new. They are basically similar to models of traditional payment processors and fintech companies. The difference is that stablecoins are used as backend settlement tools, reducing friction between countries, currencies, and financial institutions.
For VCs, this means companies can be evaluated using familiar metrics. For example payment volume, net revenue, gross margin, customer retention rate, and cost per transaction. Compared to projects heavily relying on market cycles and token prices, these businesses are easier to evaluate. They are also easier to explain to traditional tech and fintech investors.
3. Stablecoins Are Becoming an Invisible Backend Tool
Early stablecoin payment processes usually required users to first buy stablecoins, then transfer to wallets, then find merchants willing to accept crypto. This required users to understand blockchain, wallet addresses, networks, and Gas fees. This constituted a large adoption barrier.
Companies that recently secured funding are attempting to hide these steps.
Félix Pago users can initiate remittances via WhatsApp. Rain and RedotPay connect stablecoins with payment cards. Mesh allows users to pay with one crypto asset, merchants receive another stablecoin. OpenFX mainly serves fintech and remittance companies, end users may not even know settlement involves stablecoins.
Therefore, VCs are not necessarily betting that consumers will actively choose to pay with stablecoins. Instead, they are betting stablecoins can replace parts of traditional payment and clearing processes in the backend. Users may still use cards, bank accounts, local currency, or communication apps.
4. Regulatory Changes Expanded Potential Customer Base
Previously, regulatory uncertainty limited the ability of banks and large payment institutions to adopt stablecoins.
Regulations increased costs related to reserves, audits, AML controls, and licenses. Meanwhile, clearer rules make it easier for banks, enterprises, and payment companies to judge what activities they can conduct.
For institution-facing companies like Stablecore, Ubyx, and Rain, regulatory clarity expands potential customer base from crypto companies to banks, fintech platforms, and traditional enterprises.
This also helps explain why recent investor lists include not only crypto-native institutions like Dragonfly, Galaxy Ventures, and Paradigm. But also traditional tech and fintech investors like ICONIQ, Accel, Lightspeed, QED Investors, and Norwest.
5. Payment Company Acquisitions Improved Exit Visibility
In February 2025, Stripe completed acquisition of stablecoin infrastructure company Bridge. Media reports stated this deal was valued at about $1.1 billion. Bridge helps enterprises issue, manage, and transfer stablecoins. Subsequently Stripe integrated these capabilities into its payment products.
In March 2026, Mastercard announced agreement to acquire stablecoin infrastructure company BVNK for up to $1.8 billion. This includes $300 million in contingent consideration. BVNK connects stablecoins, fiat, banks, and multiple blockchains. It provides cross-border payment and settlement services for enterprises.
These acquisitions are important for VCs. Because potential exit paths for stablecoin payment companies are no longer limited to token issuance or IPO. They may also be acquired by card networks, payment companies, banks, or large fintech platforms.
These deals also prove the value of licenses, local banking relationships, and existing customer networks. Traditional payment companies can develop blockchain technology internally. But establishing compliant operations and liquidity networks in multiple countries may take years. Acquiring a company that has already built this type of infrastructure may be faster.
Why Might the Stablecoin Payment Boom Be Overestimated?
Stablecoin payments bring clear opportunities. But certain parts of the funding narrative may be exaggerated.
1. Stablecoin Volume Does Not Equal Payment Volume
On-chain stablecoin activity includes exchange transfers, market making, arbitrage, DeFi, smart contract interactions, institutional fund flows, and ordinary payments. Even after filtering out some bot activity and repeated transactions, remaining volume cannot all be classified as payments for goods and services.
Visa previously pointed out that as of March 2025, in the preceding 12 months, retail-level transactions accounted for less than 1% of adjusted stablecoin volume.
Stablecoin volume exceeding card network volume does not prove stablecoin payment activity has surpassed Visa or Mastercard. These data measure different types of activity and cannot be directly compared.
2. Funding Concentrated in Few Companies
Rain raised $250 million in a single round. RedotPay raised $194 million total in 2025. OpenFX raised $94 million in a single round. A few large deals can significantly push up total funding amount for the industry. But this does not mean every stablecoin payment startup can easily secure funding.
Rain, RedotPay, and OpenFX all reported rapid growth. Investors are supporting companies that have already formed a certain scale. Early projects without licenses, local payment channels, or actual customers still face difficult funding environments.
In other words, this is more like capital concentrating towards market leaders, rather than a comprehensive boom across the entire stablecoin payment industry.
3. Core Services May Rapidly Commoditize
Technical barriers for wallets, stablecoin on/off ramps, cross-border transfers, and payment APIs are declining. More and more companies can provide similar functionality. Banks, exchanges, stablecoin issuers, and traditional payment companies are also building their own products.
If multiple platforms can all handle USDC or USDT transfers, only providing on-chain payment APIs may not form a lasting competitive advantage. Companies ultimately need to compete on licenses, local banking connections, FX pricing, payment success rates, risk control, customer service, and costs.
As competition intensifies, transaction fees and FX spreads may narrow. Payment volume growth will not automatically translate into high profits.
4. Global Expansion Still Requires Market-by-Market Implementation
Blockchains can operate cross-border, but bank accounts, licenses, and fiat currencies do not automatically globalize.
When each stablecoin payment company enters a new market, it still needs to establish relationships with local banks, payment institutions, and liquidity providers. It must also comply with local KYC, AML, sanctions screening, data protection, and consumer protection requirements.
If local banks terminate cooperation, or on/off ramp channels are unavailable, on-chain funds may have arrived. But still cannot be exchanged into fiat currency needed by customers.
Stablecoins mainly improve the intermediate settlement layer. They will not completely replace the traditional financial system.
5. Traditional Financial Institutions Are Both Customers and Competitors
Banks and card networks are currently investing in or acquiring stablecoin infrastructure companies. They hope to quickly obtain these capabilities. However, as technology and regulatory frameworks mature, these institutions may also build systems themselves. They will also integrate stablecoin functions into existing products.
Stripe, Visa, Mastercard, PayPal, and major banks already possess merchants, accounts, trusted brands, and regulatory resources. Startups may become their suppliers or acquisition targets, but may also be pushed into lower margin backend service roles.
Where Might Capital Flow Next?
Recent funding activity indicates investment is shifting from issuing more stablecoins, to introducing stablecoins into bank, enterprise, and user accounts.
Several areas may continue to attract attention.
First is cross-border B2B payments. Compared to consumer payments, enterprise transaction sizes are larger, more sensitive to settlement speed, working capital needs, and FX costs. Enterprises are also more willing to pay for measurable efficiency improvements.
Second is connections between banks and stablecoins. The opportunity represented by Stablecore and Ubyx is enabling banks to receive, send, clear, and redeem stablecoins. These stablecoins are issued by different entities and operate on different blockchains.
Third is stablecoin-linked cards and local payments. Users do not need to find merchants that directly accept stablecoins. They can spend via existing card networks and acquiring networks. Rain and RedotPay completed financing successively. This indicates bank cards remain one of the most direct pathways for stablecoins to enter daily payment scenarios.
Fourth is multi-stablecoin, multi-chain orchestration layer. Enterprises usually do not wish to integrate USDT, USDC, multiple blockchains, and on/off ramp providers from various countries separately. Platforms capable of managing asset selection, routing, fees, compliance, and exchange through a unified interface may attract more institutional customers.
Fifth is AI agent payments. Processes like verification codes, bank card verification, and manual authorization in traditional payment systems are usually not designed for AI agents. Stablecoin wallets and programmable payments can provide another settlement mechanism.
However, this field is still mainly driven by infrastructure development and expectations. Actual payment demand and revenue still need to be proven.
VC interest in stablecoin payments does not mean the crypto funding winter has ended. It also does not mean stablecoins have replaced traditional payment systems on a large scale.
More accurately, as funding environment tightens, investors are starting to look for a type of company. They can operate independently of token prices, solve real financial problems, and generate recurring revenue.
Stablecoins provide a global programmable settlement asset that operates 24/7. The opportunity for startups lies in connecting stablecoins with bank accounts, FX markets, payment cards, local currencies, and compliance systems.
Next stage valuations will not only depend on funding rounds or on-chain transaction volume. It will also depend on how much of these volumes represent real customer payments, how much net revenue is generated. It depends on how many regulated markets the company can enter, and whether it remains profitable after deducting liquidity, distribution, and compliance costs.
Crypto VCs are not necessarily betting that one specific stablecoin will win. They are betting that the massive infrastructure required to integrate stablecoins into the real-world financial system has not yet been built and fully matured.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 吴说区块链